Now I’m wondering if it makes any sense to double up on insurance.
Like finding a second company and getting a policy from them also.Ultimately it’s all Lloyds of London. They insure pretty much every insurance company.
Loyd’s runs an insurance brokerage or market, they don’t actually underwrite the policies themselves.
He’s talking about reinsurance. Front-line insurance companies that you typically deal with directly are (sometimes? often?) “reinsured” by other insurance companies backing their risks. It’s turtles all the way down.
They also insure the insurance companies themselves. Insurance companies have to get payout insurance, for if they have to do a big payout.
Depending on what it’s for, how much it’s for, and if allowed by laws, perhaps consider self-insurance.
Economic collapse as lateral damage.
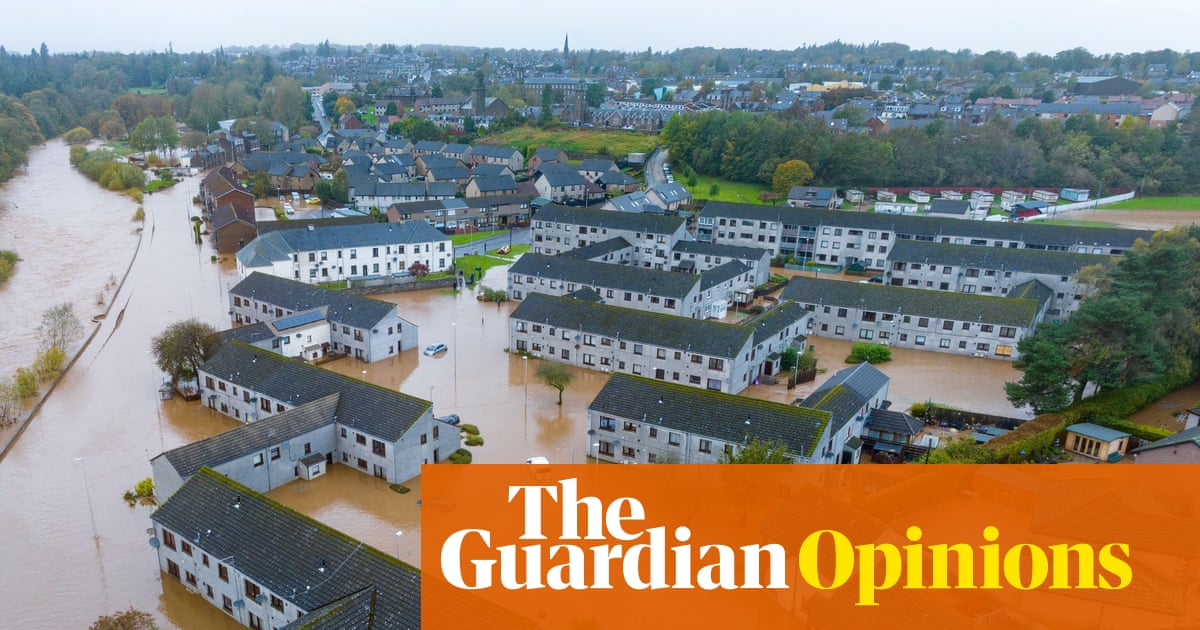
This article makes no mention of reinsurance, the insurance insurance companies buy from reinsurance companies. Basically they’ll take out reinsurance policies from companies like Loyds of London to cover them in case there’s a catastrophe, such as a hurricane destroying an entire city, so they can still pay out the claims.
Seems a little odd it isn’t mentioned in this article.
When my insurer gives me tips on how to reduce my gasoline consumption, I tell them to stop investing in O&G producers.
If they were investing in them, they would want you to use more?